Posts

Showing posts with the label job history

Kentucky USDA Rural Housing Mortgage Qualifying Guidelines

Image
Kentucky USDA Loans 2026: Zero Down, Income Limits & How to Qualify | Joel Lobb Home › Loan Programs › Kentucky USDA Loans 2026 ✅ Updated March 2026 Kentucky USDA Loans 2026: Zero Down Payment, Income Limits & How to Qualify The complete guide to Kentucky's most powerful no-down-payment mortgage program — eligibility, income limits, credit requirements, and how to get pre-approved today. 0% Down Payment 0.35% Annual MIP $119,850 Income Limit (1–4) 640 Typical Min Score 📋 What's In This Guide What Is a Kentucky USDA Loan? Key Benefits in 2026 2026 Income Limits by County Full Eligibility Requirements Mortgage Insurance Comparison 3 Types of USDA Loan Programs Step-by-Step Loan Process Pre-Approval Document Checklist Frequently Asked Questions Get Pre-Approved Today 🎥 Watch: Kentucky USDA Loan Overview — Joel L...
Louisville Kentucky Mortgage Lender for FHA, VA, KHC, USDA and Rural Housing Kentucky Mortgages: Job History and Income Requirements for a Kentucky...

Image
Louisville Kentucky Mortgage Lender for FHA, VA, KHC, USDA and Rural Housing Kentucky Mortgages: Job History and Income Requirements for a Kentucky... :    Job History and Income Requirements Kentucky Government Mortgage FHA, VA, USDA and Fannie Mae   Mortgage Home Loan Job History Kentucky Government Mortgage FHA, VA, USDA and Fannie Mae   Mortgage Home Loan Job History & Income Requirement Breakdown

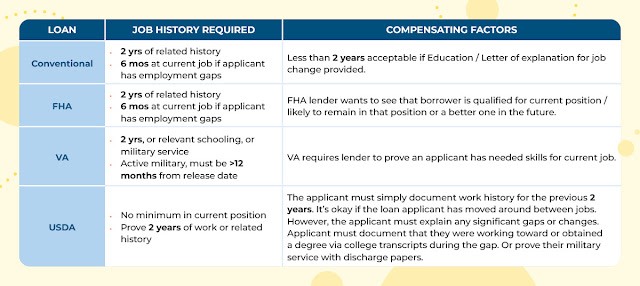
Employment job history requirements for a USDA Loan Approval In Kentucky

  Kentucky USDA Mortgage Program The USDA Home Loan Program does not technically have an minimum employment history requirement but lenders are required to verify applicants' employment history for the prior two years and confirm that the applicant's income is stable Applicants are required to explain any employment gaps of at least one month Explainable employment gaps of six months or more are also permitted as long as the applicant can document the reason for the gap, has been back to work for at least six months and has a two year employment history prior to the work gap Self-employed borrowers are typically required to demonstrate a two year job history as documented by the applicant's tax returns A self-employed job history of between one and two years is permitted if the applicant was previously employed in a similar line of work for at least two years or one year of work plus one year of formal education or training The lender is required to confirm that the self-em...

Kentucky USDA Rural Development Loans Program Guidelines

Image
Kentucky USDA Rural Development Loans Program Guidelines Loan Purpose of Kentucky Rural Housing Loans Purchase One-time Close Construction Loan (very few lenders do this) Rate-term refinance for existing USDA Loans Only. Cannot refinance a Conventional loan, FHA, VA, or other loans into an USDA loan.  Credit Profile for a Kentucky Rural Housing Buyer 581 minimum middle credit score for all borrowers on the loan – purchase No score allowed with alternative trade lines Most Kentucky USDA lenders will want a 620 or 640 score or higher. A 640 middle score is required for a USDA loan through GUS, the automated underwriting system used by rural development to determine the max lending limits for a loan.  No foreclosure, short sale, or Chapter 7 bankruptcy discharge within three years of contract ratification date on credit report not permitted Minimum of two tradelines on credit, with a positive pay history within the most recent 12-month period. Accounts can be...

What are the income and employment guidelines for a Kentucky Rural Development Loan Housing Approval?

Image
What is an acceptable income and employment for a KY USDA Loan Approval?  There is no minimum length of time an applicant must have held a position to  consider employment income as dependable.  Lender must verify the applicant’s employment for the most recent 2 full years & verify that the applicant’s income has been stable.  The applicant should not have any gaps in employment of more than a month  within the 2 year period prior to making the loan application.  Applicants that have not been employed for 12 months with their current employer or have experienced a significant earnings increase are considered high risk. • Second jobs, full 2 year history • Unearned income, 3 year continuance • Self‐employed applicants, 2 year history Newly Employed: Less than a 2-year employment & income history can be considered when documentation = applicant was attending school immediately prior to current employment. School Program/Classes mus...